Profit Loss Form AlternativeWhat actually came in.
The lender asked for a current profit and loss statement, and the top line is a total of deposits that were never all sales.
Show what came inShow what came in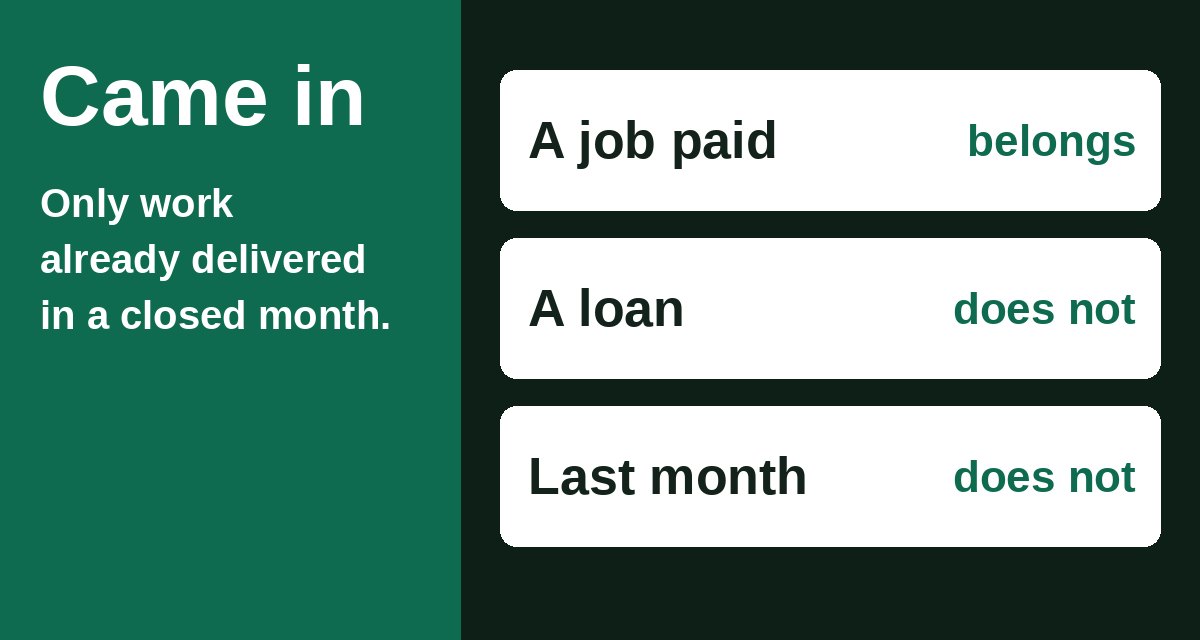
What arrived in the account is not the same as what the shop earned.
Click to read the deposits ›Tap to read the deposits ›
The first line of the page is what customers paid for work you delivered in the closed month. A card batch that ties to those jobs belongs there. A check from a customer for a job that left this month belongs there. The support under the line is a list that names each deposit and the job it came from.
Three arrivals often get parked on that line by mistake. A loan that funded the account. A transfer from a savings account the owner already owned. A sale from last month that happened to clear this week. None of those is revenue for this month. They explain the bank. They do not explain the work.
The month has to be closed before the line is finished.
Click to read the close ›Tap to read the close ›
If the statement is not in, the first line is a guess about which deposits exist. We wait for the statement and then we tick the deposits against the jobs. A deposit with no job stays on the uncleared list until someone can say whose money it was.
Owners sometimes total the deposits and call that the month. That total includes everything that arrived, including money that was never a sale. The page we will hand over uses the smaller, named figure. The difference is written down beside it so a lender can see we did not hide the gap. Bring the deposit list for this month with each job named beside it. Two blank lines are more useful to us than a round total nobody can trace to a customer. A deposit you cannot name stays off the first line until the job is known.
Where the deposits came from

You will be talking to the Steven Palmieri practice.